Subscribe to Industry Today’s regular e-newslettersindustrytoday.com
Subscribe https://industrytoday.com/wp-content/uploads/2026/10/BAT_Construction_728x90@2x.png
Why is construction attracting more private equity, and what are today’s buyers looking for in the companies they acquire?
By Mike Reynolds, Partner, Financial Reporting and Assurance, and Connor Gibson, Director, Transaction Advisory Services, at national accounting and advisory firm Bennett Thrasher

Construction executives are navigating a business environment that is making ownership and growth decisions increasingly complex. For years, private equity firms were cautious about the industry, shying away due to the industry’s historical complexity and difficulty to underwrite.
That dynamic is changing as more investors become comfortable with the risks associated with the industry’s long-term projects, shifting margins and capital requirements. Private equity firms may also be in need of new opportunities to deploy capital, prompting them to consider industries and business models they previously overlooked. But private equity alone isn’t driving the increase in transaction activity, as changes within the construction industry itself are giving owners more reasons to consider a deal.
Many established owners are reaching an inflection point, facing rising costs, labor shortages and the question of what comes next. The result is a growing alignment between what construction companies need and what institutional capital can provide.
Many construction businesses were built over decades by owner-operators who are now approaching retirement, often without a clear internal or family successor. Part of this challenge is due to labor shortages following the Great Recession and recent immigration enforcement, leaving fewer experienced people available to step into leadership roles.
For some owners, selling to an outside buyer is a way to monetize what they’ve built rather than simply closing shop. But not every owner considering outside capital wants to retire. Some businesses have simply reached a point where they need additional resources or technology to reach their next stage of growth, making today’s construction M&A market a mix of growth-oriented owners and those pursuing an exit.
Several forces are converging to make construction a hot investment target. As health care and data center construction continue to be major areas of activity, investors are expanding their focus beyond project contractors to adjacent companies across the construction ecosystem, including product manufacturers and suppliers, installers and specialized service providers.
This is creating consolidation opportunities for fragmented, construction-adjacent businesses as strategic buyers combine complementary services at scale. We saw this happen with HVAC businesses in recent years, with buyers attracted to their predictable, recurring revenue and diversified customer base.
At the same time, potential buyers are becoming increasingly comfortable with evaluating the financial uncertainties traditionally associated with construction companies’ progress billings, project backlogs and shifting margin projections.
Beyond earnings, buyers want to know whether a construction business can deliver long-term performance after the deal closes. Several factors stand out:
What defines a successful transaction varies by owner. Some prioritize maximum sale value, while others care deeply about preserving their company’s culture, leadership team and legacy. Many want to stay involved while bringing in outside capital to support the company’s next era.
That is why the buyer is being evaluated, too. Owners want a buyer who will carry forward their vision, and who can explain how they plan to grow the business while preserving what made it successful and supporting employees through the transition.
Importantly, a merger or acquisition doesn’t always mean a complete exit. Owners can consider a minority investment, an Employee Stock Ownership Plan (ESOP), or family succession. That’s why transaction interest can often help determine what’s next and what’s truly best for an organization.
Looking ahead, construction M&A is likely to remain shaped by the same forces driving activity today: an evolving labor market, an aging ownership base, demand for growth capital and increasing interest from institutional buyers. As that interest grows, buyers will continue to place a premium on construction companies with predictable performance, strong financial visibility, experienced management teams and the operational infrastructure to support growth. For owners, that means the range of potential paths forward is expanding – from a full exit to outside investment, succession or continued independent growth. Ultimately, the changing M&A landscape is giving construction executives more opportunities to determine what the next chapter of their business looks like.
About the Authors:
Mike Reynolds is a Partner in Bennett Thrasher’s Financial Reporting & Assurance practice, where he supports construction clients with audits, reviews and compilations as well as consulting, due diligence and internal audit engagements.
Connor Gibson is a Director in Bennett Thrasher’s Transaction Advisory Services practice, where he advises both strategic and private equity investors on buy-side and sell-side transactions.
Read more from the authors:
Accountants help construction companies field PE offers | Accounting Today, October 1, 2026
Forging the Next 250 Years: Powering the Next Era of American Manufacturing
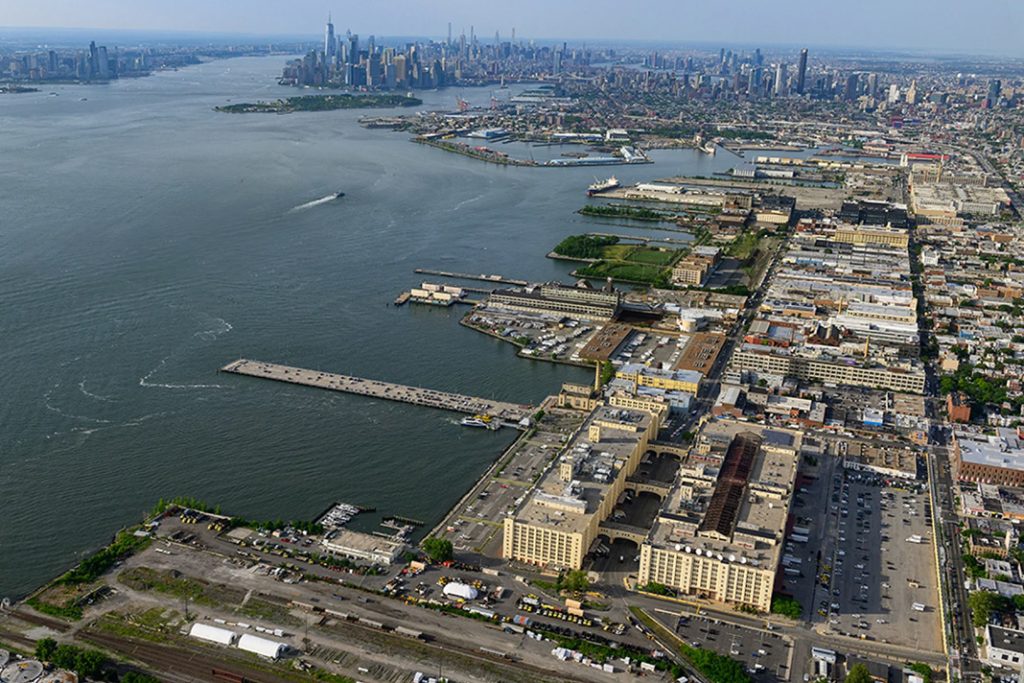
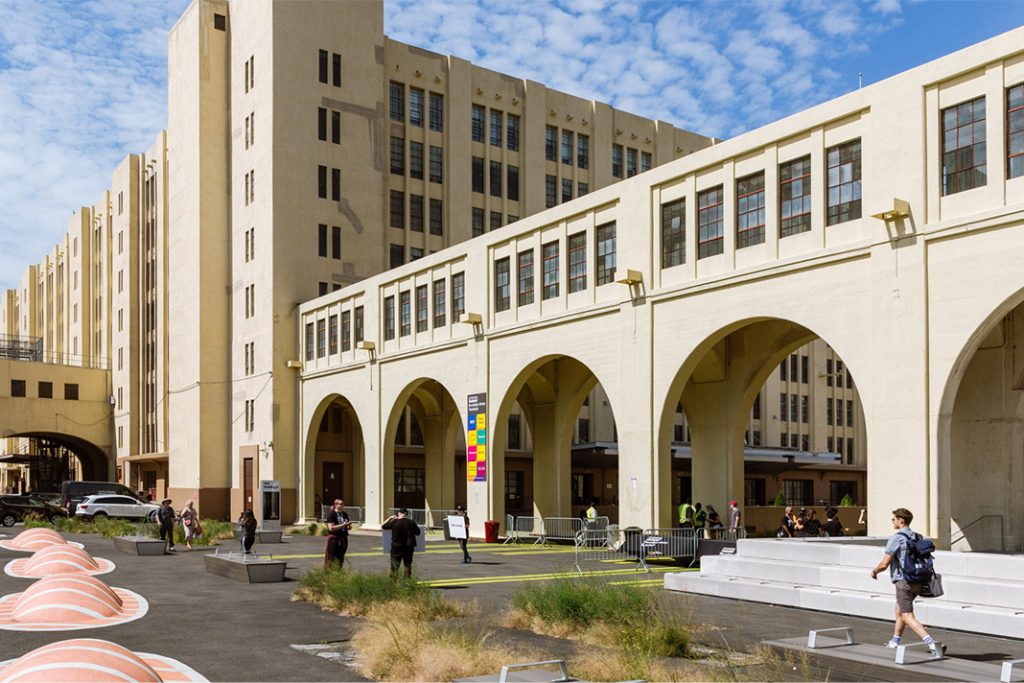
Brooklyn Army Terminal (BAT) began as a World War II-era military supply base. Today it is New York City’s largest publicly owned industrial campus, with 59 waterfront acres, more than 4 million square feet and over 100 businesses. In this episode of Industry Insights, Bridget Chansakul, Vice President of Leasing & Portfolio Management at NYCEDC, explains what space is available and what’s planned for the 250,000+ square feet of new industrial space in Building A. She also covers how the ferry, parking and on-site childcare help tenants hire and keep workers, along with workforce partnerships, City incentives for manufacturers and where BAT is headed next.
Get In Touch
Google news and SEO compliant, Industry Today’s state-of-the-art digital media platform offers bespoke media campaigns that target key decision makers and buyers to achieve your marketing and promotional goals.
Contribute
Showcase your brand and promote your business to our highly targeted audience. We offer detailed Google Analytics with measurable ROI to assure success. Submit your content for review by our Editorial team who will contact you to discuss the project further.
About Us
Reach Your Targeted Audience and Grow Your Business. Learn more About Industry Today.
Contact Us
© 2026 Industry today. All Rights reserved.